
Essential Steps to Secure a Mortgage Loan in Nigeria
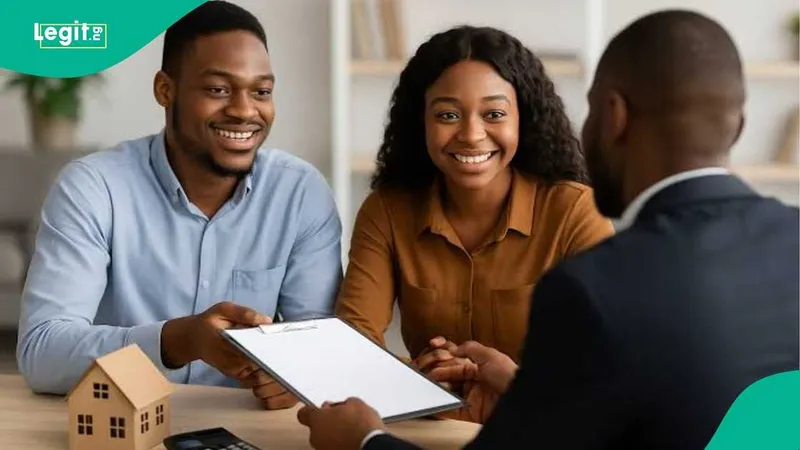
In Nigeria, securing a mortgage loan involves meeting specific requirements set by lenders, which can vary based on the institution and the applicant's financial status. Applicants must generally be between 21 and 60 years old.
Proof of employment, including position, length of service, and salary, is required for employees, while business owners must provide profit and loss statements. Lenders typically request bank statements from the past six to twelve months to evaluate income and spending habits.
A healthy credit record is crucial, as it reflects the applicant's financial responsibility. Borrowers are usually expected to contribute 20% to 30% of the property's cost as a down payment.
For instance, purchasing a property valued at ₦50 million may necessitate a down payment of ₦10 million to ₦15 million. Additionally, lenders require documentation to confirm the legal ownership of the property, such as a Certificate of Occupancy (CofO) and title deed, to mitigate risks associated with financing disputed properties.
Plus234Feed summary based on reporting from Legit.ng. Read the original report below.
Read full article
Continue on Legit.ng
Get the week in one email
Top stories, NPFL results, the naira, every Friday morning. Free, one email a week.
Related Stories
How to Apply for FG Mortgage Loan in Nigeria
Nigerian Government Advocates Mortgage Reforms for Housing

Top Banks Offering Home Loans in Nigeria for 2026
CreditRegistry Reveals Reasons for Loan Application Rejections
Top 7 Nigerian Banks Offering Car Loans with 10% Deposit
Nigerian Government Proposes Reforms to Boost Homeownership
Get Plus234Feed on messaging apps
Same headlines, delivered where you already scroll.