
Nigerians Face Debt Crisis Amid Rising Loan Demands

Nigerians are facing a severe debt crisis as loans taken for essential needs such as food, rent, and education have become a debt trap. Traders report business failures, while civil servants experience significant deductions from their salaries.
The Central Bank of Nigeria (CBN) revealed that personal loans surged to approximately N2.06 trillion, making up nearly two-thirds of consumer credit. This rise occurs amidst weak consumer spending and declining household incomes.
The CBN's Economic Report for May 2026 indicated that economic activity remains weak, with a Purchasing Managers’ Index of 49.60 points. Borrowing for consumption purposes increased from 31.7% to 40.8%, while productive borrowing fell.
The report also highlighted that 45.8% of formal credit users face repayment stress, and 83.8% experience ongoing financial stress. Many Nigerians are now using loans primarily to meet urgent personal obligations rather than for business financing.
Plus234Feed summary based on reporting from Leadership Newspaper. Read the original report below.
Read full article
Continue on Leadership Newspaper
Get the week in one email
Top stories, NPFL results, the naira — every Friday morning. Free, one email a week.
Related Stories
EFInA Survey Reveals Rising Borrowing for Daily Needs
Nigerians Increasingly Rely on Loans for Daily Needs
EFInA Survey Reveals Shift to Consumption Borrowing in Nigeria
Nigeria's Debt Hits N166.79 Trillion, Burden Per Citizen Rises
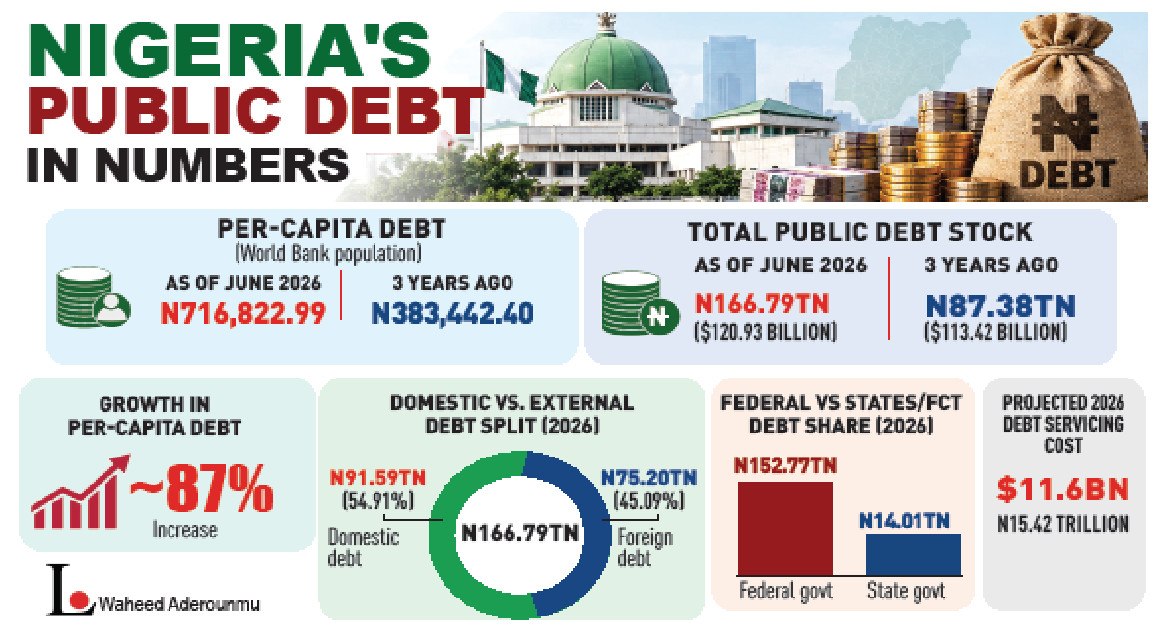
Nigeria's Debt Per Citizen Surges to N716,822 in 2026
CBN Survey Shows Nigerians Favor Food Spending Over Investments
Get Plus234Feed on messaging apps
Same headlines, delivered where you already scroll.


